Gold prices rebounded 1.1%, weathering COT reduction and rising real interest rates.
① One-sentence summary for this week:
Gold prices rebounded 1.1% on a weekly basis. While institutional investors reduced their long positions and real interest rates rose, the price finished at $4,424.9, absorbing mid-week downward pressure. The resilience of prices despite multiple headwinds suggests a firm floor for this week.
② Price Trends and Chart Review
This week’s gold futures reference values rose from $4,375.0 on Monday, September 14th, to $4,424.9 on Friday, September 18th, resulting in a weekly gain of +1.1406%. The high for the week was $4,439.8, and the low was $4,273.3. The range from the low to the high was $166.5, or 3.8057% from the week’s opening value. While briefly falling below $4,300, the recovery of approximately $151.6 from the low provided a stronger impression than a simple slight increase.
Previously, we identified whether gold could recover to the $4,500 level, whether real interest rates would decline from 2.60%, and whether the Commitment of Traders (COT) report would increase as observation points. The results were that gold did not recover above $4,500, real interest rates rose to 2.68%, and the COT report decreased, meaning none of the conditions improved. Nevertheless, the price exceeded $4,408.9, the previous week’s close. While a sustained rally was not confirmed, the resilience to adverse conditions was verified.
The closing price is up +5.2871% compared to three months ago, and +20.0968% compared to one year ago. It is at the 83.03 percentile over the past three years, and in a high price range when viewed over a longer term. The 20-day annualized volatility is 19.6026%, at the 65.17 percentile over the past three years. While volatility eased compared to the previous week, daily price fluctuations remain significant, and it is important to observe not only the direction but also the extent of the rebound from lows.
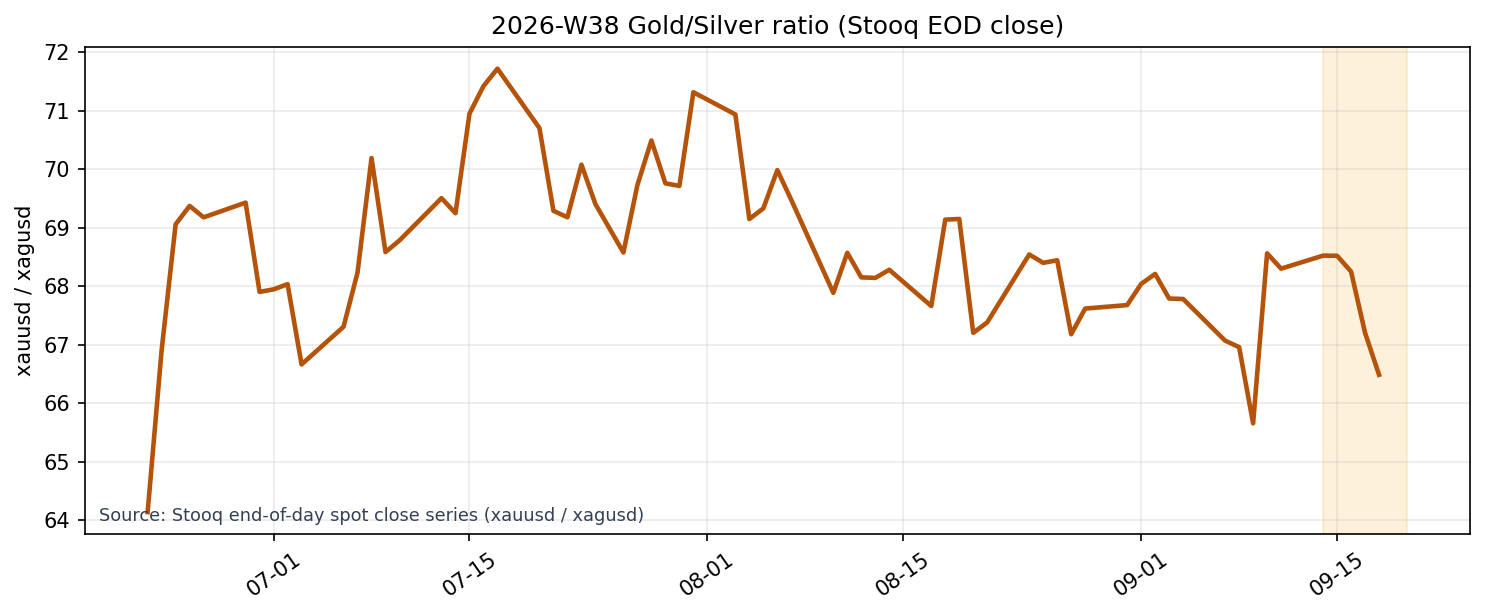
Source: Stooq end-of-day spot close series (xauusd / xagusd).
The chart uses spot prices from the Stooq EOD closing data. The gold-silver ratio is 66.4839, down 2.6560% week-on-week. Gold rose, but silver’s increase was stronger, indicating a more significant rise. Gold’s rebound may have been due not only to defensive demand but also to a partial return of funds to precious metals overall.
③ Investor Activity
CFTC COT (as of September 15) showed that money managers held 142,394 long contracts, 9,278 short contracts, and a net long position of 133,116 contracts. This decreased by 1,856 contracts from the previous week, marking a two-week consecutive decline. Despite the price rebound, the net long position has not increased, and this week’s rise cannot be explained solely by active buying from institutional investors.
Net positions are at the 80.77th percentile over the past year, remaining in the top roughly 20% of levels. While a substantial long position is maintained, there is not an unlimited scope for additional buying. Long positions decreased from 145,804 contracts the previous week, while short positions also decreased from 10,832 contracts, indicating a simultaneous retreat by bullish and bearish investors. Next week, it will be important to observe not only the net position but also which side – long or short – will lead the change.
④ Macro Factors Check
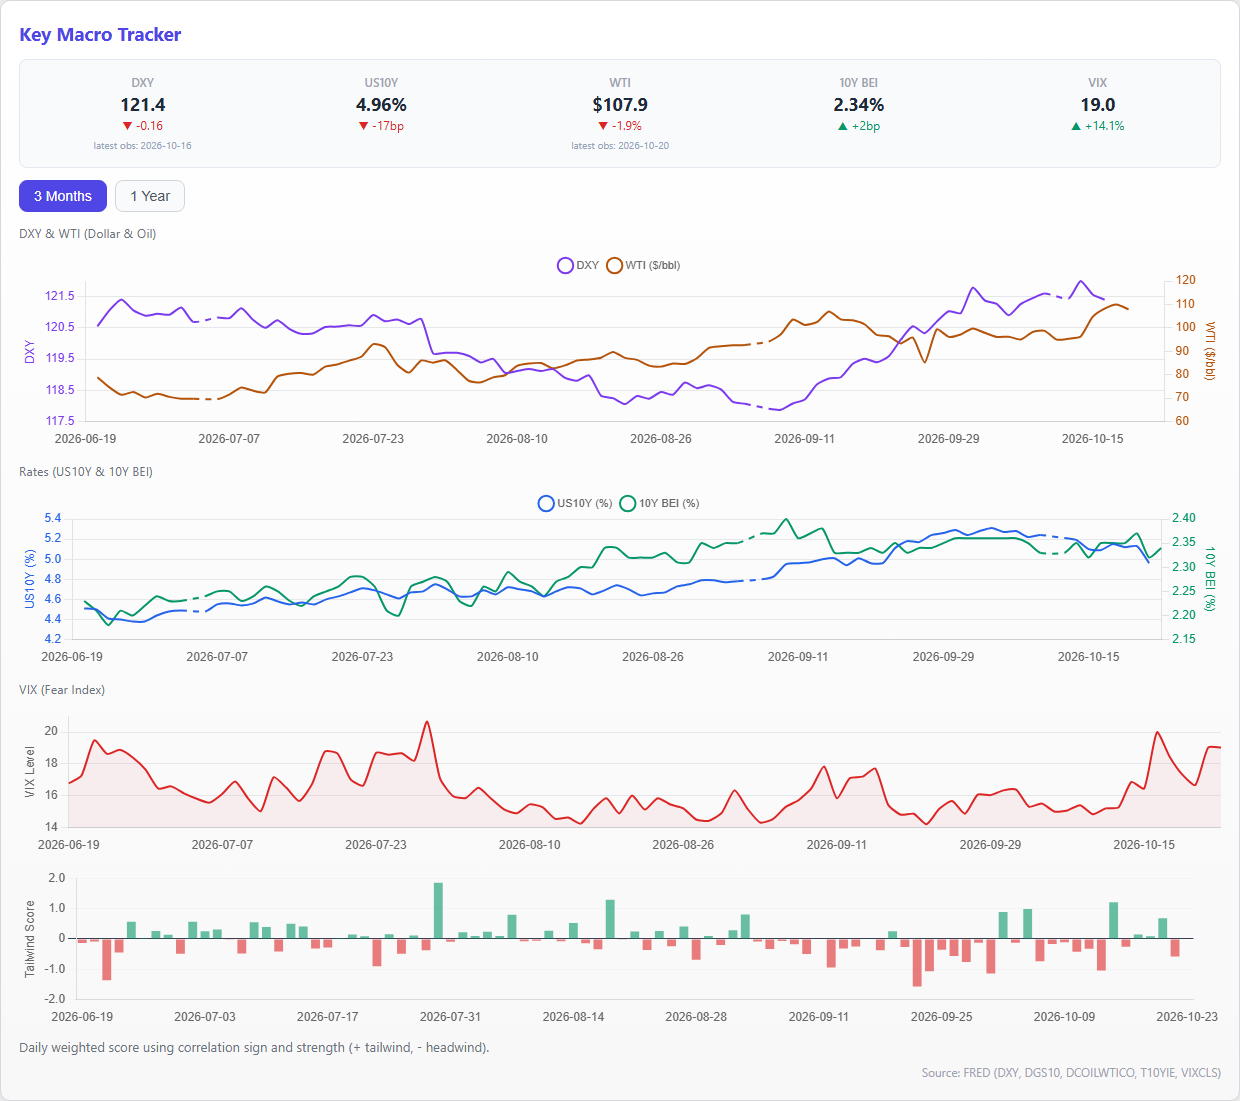
Macroeconomic factors are not straightforward tailwinds for gold. The DXY is at 119.5133, a 0.1377% rise from the previous observation. The US 10-year nominal interest rate is 5.01%, the breakeven is 2.33%, and the real interest rate is 2.68%, up from the previous 2.60%. This is a burden for interest-free gold.
Meanwhile, the VIX is at 14.81, and the US high-yield bond spread is 2.68%, indicating no widespread fear or credit concerns in the market. WTI is at $101.44, a 1.7150% decline from the previous observation. It is more natural to view this week as one where gold-specific or overall precious metals demand absorbed the headwinds from interest rates and the dollar, rather than a full-scale flight to safe assets.
⑤ Supply and Demand and Sentiment
This week's gold-related articles numbered 37. Site-adjusted news sentiment was +0.0686 on a weekly average, with a recent value of +0.05, slightly positive. This is a clear cooling from the previous week’s weekly average of +0.6714 and a recent value of +0.91, indicating that news sentiment is not accelerating the price rebound. While the price was not driven up by enthusiasm, a lack of bullish factors also does not guarantee future gains.
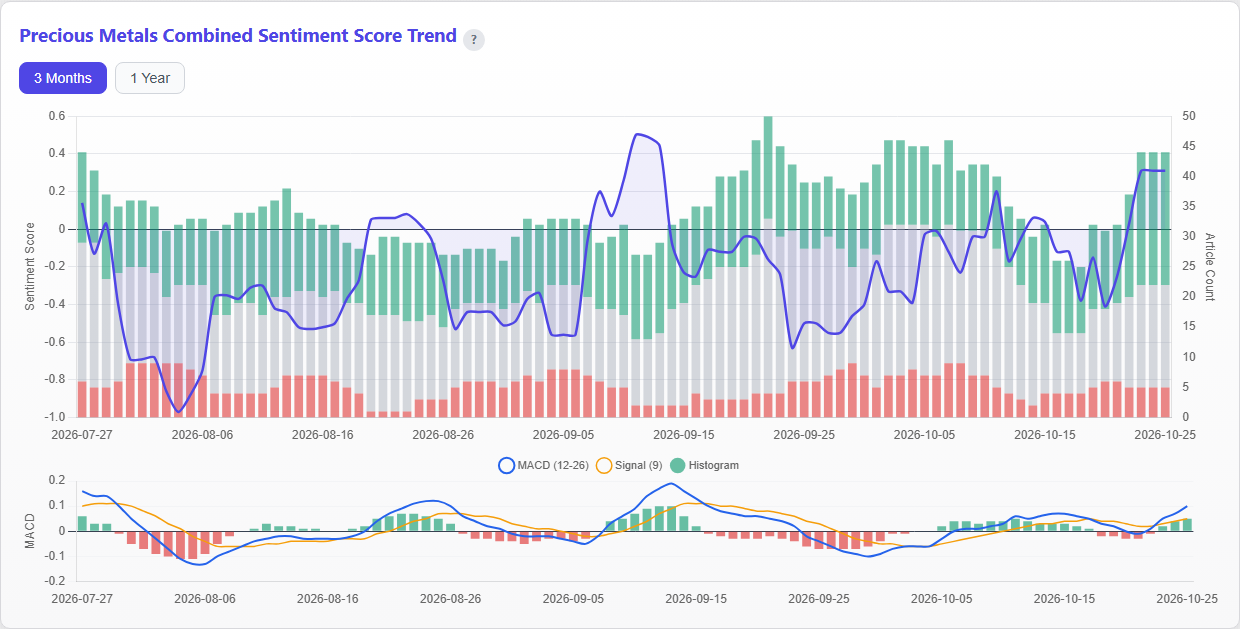
COT net long positions decreased by 1,856 contracts compared to the previous week. This means that while prices rose, news sentiment and institutional flows were weak. If this divergence continues, confirmation will be needed for a sustained rebound, and if COT reductions stop and sentiment turns upward again, it will be supported by supply and demand factors in this week’s firmness.
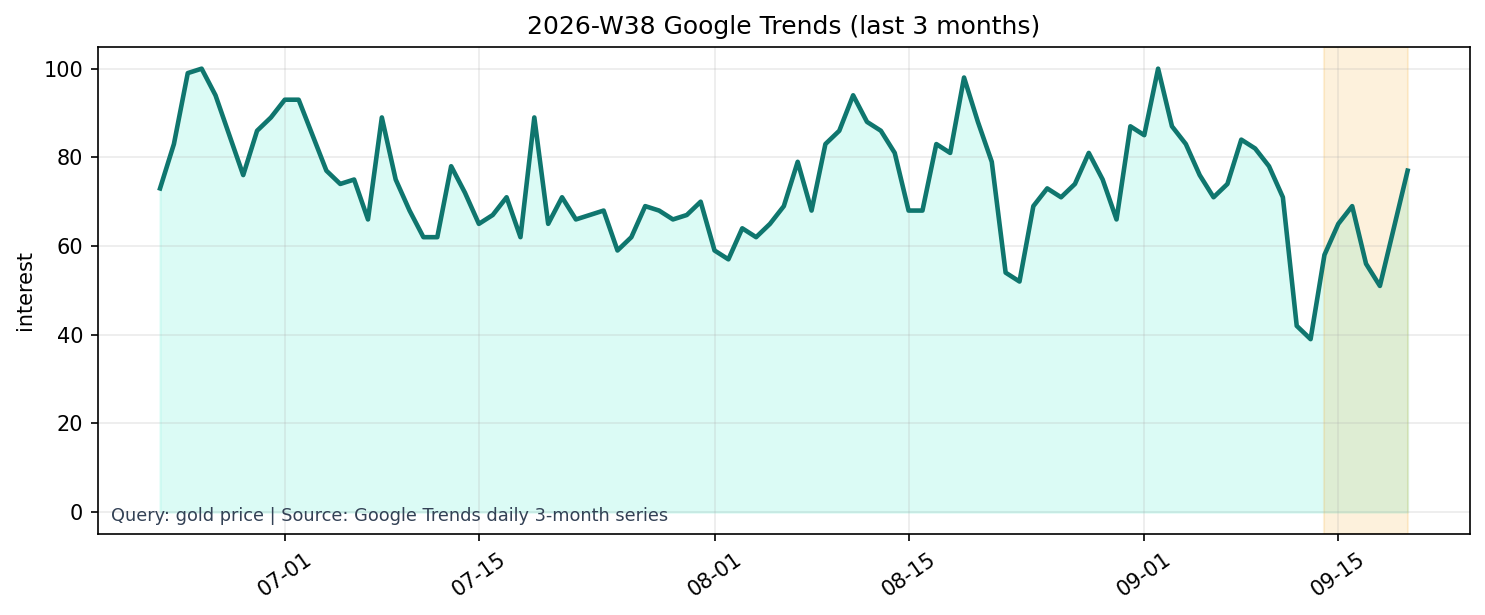
Source: Google Trends daily 3-month series (gold price).
Google Trends’ “gold price” search interest was 77 for the 3-month series, a 20.3125% rise from the previous value of 64. However, the 1-year series was 21, an 8.6957% decrease from the prior week’s 23. Trends vary depending on the period; recent daily search interest has recovered, but broader weekly search interest remains weak. Recent increases in search volume do not yet indicate a full-fledged surge of enthusiasm among retail investors.
⑥ This Week’s Insights and Next Week’s Highlights
The core focus this week was the misalignment between price direction and surrounding indicators. Gold prices were +1.1406%, but COT net longs decreased by 1,856 contracts, and adjusted sentiment fell significantly from the prior week. Furthermore, real interest rates rose to 2.68%. Nevertheless, having rebounded from the weekly low, it is preferable to interpret this as residual demand absorbing selling pressure rather than simply attributing the rebound to "increased bullish factors.
The previous observation point was more challenging than expected, aside from price. This is because the recovery to $4,500, the decline in real interest rates, and the increase in COT did not materialize. However, the fact that the price did not continue to fall there is now new information. We need to retain both the fact that it held up despite weak conditions and the fact that there is a lack of flow supporting an uptrend.
Next week, we want to confirm three points. First, whether gold will surpass this week’s high of $4,439.8 and close above the $4,500 level. Second, whether real interest rates will reverse from their current level of 2.68%. Third, whether at least one of COT net longs and adjusted sentiment will improve in line with price. If only price leads, the uptrend will be unstable. Conversely, if gold holds around $4,400 while real interest rates decline or institutional flows improve, it will be easier to evaluate this week’s rebound as more than a temporary correction.
The decline in the gold-silver ratio and a short-term bounce in search interest can also be considered supporting indicators. If silver dominance continues and search interest expands, there is a possibility of increased participation in precious metals overall. If the gold-silver ratio reverses and rises, and the Commitment of Traders (COT) report and sentiment weaken further, gold's resilience may be dependent on defensive demand. This week will be about observing whether price resilience leads to actual fund flows, without rushing to conclusions.